Key Takeaways
- 01 BHP copper production fell 3% to 1,953 kt in FY2026, yet higher prices lifted copper revenue to US$29.031 billion.
- 02 Escondida produced 1,261 kt, but its concentrator feed grade is expected to fall to about 0.70% in FY2027.
- 03 BHP aspires to about 2 Mtpa of attributable copper by FY2035, subject to studies and approvals.
BHP Group Limited (ASX: BHP) remains the largest copper producer in the world. The Company produced 1,953 kilotonnes (kt) of copper in FY2026, a 3% drop from 2,017 kt. Even so, copper generated more than half of Group Underlying EBITDA for the first time. Stronger prices, not higher volumes, drove that result.
Higher Copper Prices Outweigh a 3% Fall in Output
BHP copper production fell in the year ended 30 Jun 2026, according to the BHP Annual Report 2026. Lower grades at Escondida and ore problems at Spence drove most of the decline.
| Metric | FY2026 | FY2025 |
| Copper production | 1,953 kt | 2,017 kt |
| Copper revenue | US$29.031 billion | US$22.530 billion |
| Underlying EBITDA | US$18.187 billion | US$12.326 billion |
| Average realised price | US$5.74 per pound | US$4.25 per pound |
| Underlying ROCE | 26% | 17% |
Net of price-linked costs, higher prices added US$6.7 billion to Underlying EBITDA. Lower volumes removed US$1.4 billion.
BHP Copper Mines: Escondida Leads a Five Asset Portfolio
Escondida Posts Records Despite a Planned Grade Decline
Escondida in Chile produced 1,261 kt, down from 1,305 kt. BHP holds 57.5% of the operation. Concentrator feed grade was 0.90%, against 1.02% a year earlier. Material mined and concentrator throughput still reached records.
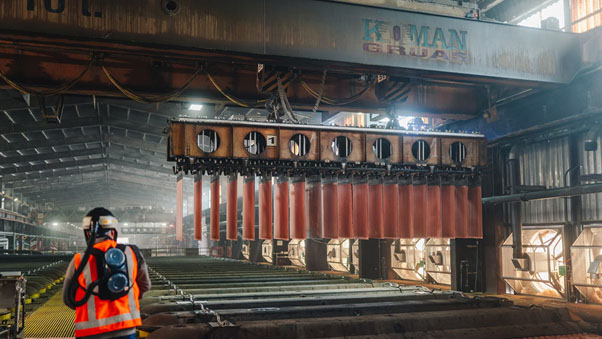
Figure 1: Copper cathode sheets are lifted from an electrolytic tank inside a processing plant. [Source: BHP]
Spence Falls 21% as South Australia and Antamina Gain
Spence produced 213 kt. Complex ore and lower stacked feed grades were behind the fall. Copper South Australia lifted payable copper 2% to 321 kt. Antamina in Peru rose 27% to a financial year record on higher feed grades.
The figures below use different bases, so they should not be added together.
| Asset | Country | BHP ownership | FY2026 copper |
| Escondida | Chile | 57.5% | 1,261 kt (total asset) |
| Pampa Norte | Chile | 100% | 213 kt (total asset) |
| Copper South Australia | Australia | 100% | 321 kt (payable) |
| Antamina | Peru | 33.75% | 151.5 kt (BHP share, payable) |
| Carajás | Brazil | 100% | 6.8 kt (BHP share, payable) |
BHP Copper Growth Pipeline Targets About 2 Mtpa by FY2035
BHP aspires to about 2 million tonnes per annum (Mtpa) of attributable copper by FY2035. That is about 40% above current levels. These are neither forecasts nor predictions; they are hopes contingent on studies and approvals.
- Escondida New Concentrator: Its annual copper capacity is targeted at 230 to 270 kt. The Company anticipates a final investment decision between CY2027 and CY2028.
- Spence Concentrator Upgrade Recovery: BHP sanctioned the project in Jun 2026. It upgrades the flotation circuit, with first production expected in FY2028.
- Spence Chalcopyrite Leaching: Sanctioned in Jun 2026. First production is expected in CY2028.
- Copper South Australia: Aspirations are about 500 kt per annum, then up to 650 kt per annum.
- Resolution Copper: BHP holds 45% and declared a 1.86 billion tonne resource at 1.52% copper.
- Vicuña: An investment decision is possible as early as the end of CY2026.
FY2027 Guidance Puts Escondida Grades in the Spotlight
BHP guides to 1,650 kt to 1,800 kt of copper in FY2027. Escondida is guided at 1,000 kt to 1,100 kt, with feed grade near 0.70%. Spence is guided at 210 kt to 230 kt.
Industry Outlook: Demand Climbs as Existing Mines Age
The Annual Report expects global copper demand to rise from about 34 Mtpa to above 50 Mtpa by CY2050. Data centre demand could grow about sixfold to roughly 3 Mtpa over the same period. Declining grades at existing mines add pressure on supply.
Grades, Ore Complexity and Execution Remain the Key Risks
- Ore grades: The Escondida grade decline drives the lower FY2027 guidance.
- Ore complexity: Spence recovery projects are yet to be delivered.
- Execution: The growth plan will come down to project earmarking of capital whilst obtaining the necessary regulatory approvals.
- Market conditions: Trade barriers and supply disruptions may change the copper market environment.
Share Price Performance
| Measure | Data (as at 19 Oct 2026) |
| Last price | A$60.33 per share |
| Market capitalisation | A$305.20 billion |
| 52-week range | A$40.175 to A$68.770 |
Impact Reaches Output, Investors and Copper Supply
Impact on the Company’s output: FY2027 volumes are guided lower before the Spence projects and Escondida New Concentrator add capacity.
Impact on ASX investors: the FY2026 earnings jump came from stronger prices, not higher output. Future results will depend on both copper prices and ore quality.
Impact on supply: BHP points to fewer new copper projects in the pipeline than in earlier cycles. Ageing mines with falling grades add to the pressure.
Mining Herald will keep tracking the Escondida decision and FY2027 production results.
ALSO READ: Mining Weekly Review: Iron Ore Costs and Copper Supply
FAQs
Q1. How much copper did BHP produce in FY2026?
Ans. BHP produced 1,953 kt, down 3% from 2,017 kt.
Q2. What are BHP’s main copper mines?
Ans. Escondida, Pampa Norte, Copper South Australia, Antamina and Carajás.
Q3. What is the BHP copper growth target?
Ans. About 2 Mtpa of attributable copper by FY2035.
Q4. Why is FY2027 copper output guided lower?
Ans. Mainly because Escondida feed grade is expected to fall to about 0.70%.
Disclaimer
This article is intended for informational purposes only. If you pay attention to the copper mining sector as an investor, then all the data in the content is from third-party sources. Please check out the complete share price and market data info. Investing carries a high risk, and you should only invest at your own risk. Mining Herald has no involvement in the above-listed companies.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.