Key Takeaways
- 01 Vale says about 10% of seaborne iron ore supply is losing money at current fuel and freight costs.
- 02 Chief Executive Gustavo Pimenta expects iron ore prices to recover as marginal producers cut output.
- 03 Vale expects base metals to rise from about 30% to more than 40% of EBITDA.
Vale (NYSE: VALE) estimates roughly 10% of seaborne iron ore supply now operates at a loss. Chief Executive Gustavo Pimenta blames fuel and freight costs. He spoke to Bloomberg Television, with the interview reported on 16 Oct 2026. At the FT Metals & Mining Summit in London, Pimenta made copper a centrepiece of the Company’s growth strategy.
Rising Iron Ore Mining Costs Push Marginal Tonnes Offline
Vale estimates the unprofitable 10% of the seaborne market equals about 160 million metric tonnes. Pimenta said roughly 15 million metric tonnes has already left the market because of the cost squeeze.
He said prices should be a little higher today. His reasoning rests on freight rates and fuel, not on supply and demand. Reports link the cost spike to the US-Iran war.
Pimenta expects prices to recover because high costs discourage output from marginal producers.
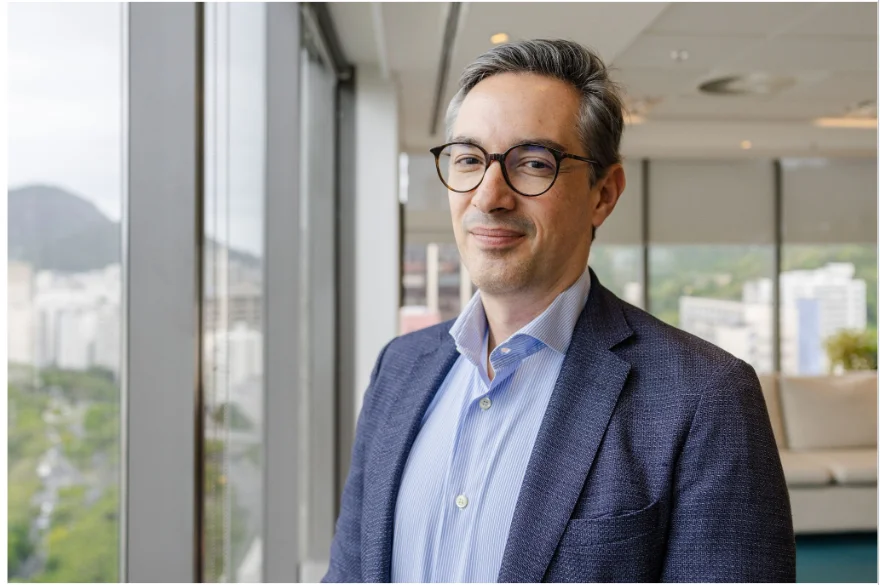
Figure 1: Vale chief executive Gustavo Pimenta [Courtesy: Bloomberg]
Weak Demand and New Guinea Supply Weigh on the Iron Ore Price Forecast
- Futures have fallen sharply in 2026 as Chinese demand weakened and global supply stayed ample.
- New output from Guinea’s Simandou mine adds further supply pressure.
- Producers face thinner margins as energy bills climb, and Vale, the largest iron ore miner, is no exception.
- Pimenta still expects a balanced market and says Chinese demand remains solid.
- He also sees strong growth in India and Vietnam.
Brazil’s Runoff and Permitting Reform Shape Vale’s Operating Backdrop
Both Runoff Candidates Described as Supportive of Mining
A presidential runoff takes place in Brazil on 25 Oct 2026. Current President Luiz Inácio Lula da Silva faces conservative Flávio Bolsonaro, who backs relaxed environmental rules. Pimenta said both candidates would support the sector and value faster permitting.
The government sold Vale into private hands in 1997 but kept a golden share. Investors also track mine permitting rules and railway concessions for signs of state influence.
Cave Rule Review Could Free a 50 Million Tonne Iron Ore Mine
Pimenta has pushed for faster permitting and more geological mapping. A review of rules that protect natural caves could unlock major projects. One is a planned Vale iron ore mine with an annual capacity of 50 million metric tonnes.
Copper Supply Outlook Gives Vale a Second Growth Story
Beyond iron ore, Vale wants more copper. Management wants base metals to carry more of the earnings load. Pimenta expects the division to climb above 40% of Vale’s EBITDA in coming years, up from roughly 30%
According to Geomechanics.io, Pimenta said Vale’s projected copper growth over the next decade tops the sector in percentage terms.
| Item | Position |
|---|---|
| Share of Vale EBITDA today | About 30% |
| Expected share in coming years | More than 40% |
| Spin-off plans | None at present |
| Vale Base Metals IPO | Depends on extra capital needs |
Spin Off Plans Hinge on Funding Needs
The Company is not planning a spin off of the division now. Pimenta said a Vale Base Metals IPO would depend on whether growth projects need extra capital.
Strategic Buyers May Follow a Credible Copper Pipeline
Geomechanics.io pointed to reports of technology groups exploring equity stakes in Anglo American for long-term copper supply. The publication suggests Vale could draw similar interest if it shows a credible copper pipeline.
Investor Risks Sit Alongside the Recovery Case
- Weaker buying or a steady flow of new mine supply could keep prices under pressure.
- Margins stay under strain while fuel and shipping bills remain high.
- Brazil’s runoff adds policy uncertainty despite Pimenta’s confidence.
- Copper growth may need extra capital, and no IPO decision has been made.
Industry Outlook Points to a Balanced Iron Ore Market
Pimenta expects the market to stay balanced, backed by steel demand in China, India and Vietnam. Vale believes prices will rebound once higher-cost producers scale back. Geomechanics.io notes that diversified peers BHP, Glencore and Anglo American have drawn more attention in copper so far.
Price Recovery and Copper Delivery Will Test Vale’s Plan
The next confirmed event is Brazil’s presidential runoff on 25 Oct 2026. Pimenta says either result should leave support for mining intact. A listing of Vale Base Metals would only follow if its expansion projects need more capital.
Impact on seaborne iron ore supply: Vale argues sustained costs could keep higher-cost tonnes offline. Impact on Vale’s earnings mix: management expects base metals to take a larger share of EBITDA.
Mining Herald will keep tracking the runoff and any update to Vale’s base metals plans.
FAQs
Q1. What did Vale say about iron ore mining costs?
Ans. Higher fuel and freight costs make about 10% of seaborne supply, roughly 160 million metric tonnes, unprofitable.
Q2. What is Vale’s iron ore price forecast?
Ans. Pimenta expects prices to recover as costs discourage marginal producers, with the market staying balanced.
Q3. What is Vale’s copper supply outlook?
Ans. Vale expects base metals to grow from about 30% to over 40% of EBITDA.
Q4. Is Vale planning a base metals IPO?
Ans. Not currently. An IPO depends on whether growth projects need extra capital.
Disclaimer
This article is intended for informational purposes only. If you pay attention to the iron ore and copper sectors as an investor, then all the data in the content is from third-party sources. Please check out the complete share price and market data info. Investing carries a high risk, and you should only invest at your own risk. Mining Herald has no involvement in the above-listed companies.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.