Key Takeaways
- 01 Capital discipline is reshaping commodity supply curves into 2026.
- 02 AI infrastructure capex is becoming a primary macro variable.
- 03 Central bank policy across AU, CA and US is converging on neutral.
The Discovery Mining stock surge narrative needs a distinction between a rising valuation target and the share price itself. On September 18, the stock was reported up just 0.1% at C$12.29 after BMO Capital increased its target from C$12.
The larger movement was therefore in the broker’s assessment, rather than the day’s trading performance.
BMO retained its market perform recommendation. Meanwhile, anticipated resource estimates at Dome and TVZ, together with Discovery’s acquisitions near Timmins, Ontario, provided the operational backdrop.
For investors, the question is whether those growth opportunities can produce results that justify the higher valuation.
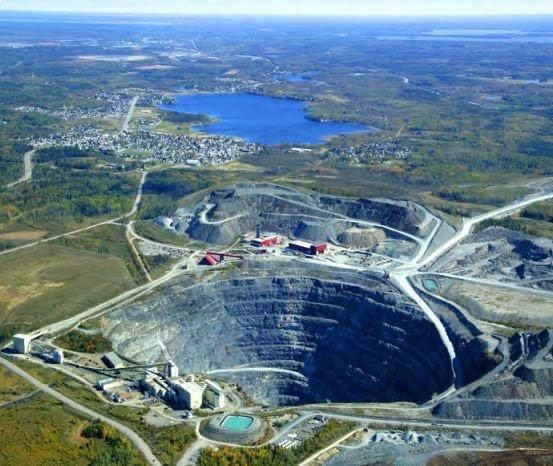
Figure 1: Aerial view of the site in the Porcupine gold district. Image source: CATT Calls.
What Does BMO’s Higher Price Target Mean for Discovery Mining?
BMO’s revision adds C$3 to its previous target, an increase of 25%. Measured against the reported C$12.29 share price, C$15 implies approximately 22.1% upside.
Those percentages describe different comparisons.
The first measures the change in the analyst’s target. The second measures the gap between that target and the quoted trading price. Neither represents a return already earned by shareholders.
| Valuation measure | Reported figure |
| September 18 trading snapshot | C$12.29 |
| Reported session gain | 0.1% |
| Previous BMO target | C$12.00 |
| Revised BMO target | C$15.00 |
| Increase in target | 25% |
| Implied upside from C$12.29 | Approximately 22.1% |
| BMO recommendation | Market perform |
The unchanged recommendation matters. A higher price target should not be presented as a new buy rating.
What “Near Highs” Would Need to Establish
Describing a mining stock near highs requires a reference point: a recent peak, a 52-week high or an all-time record.
The supplied report does not identify one. It also provides no trading-volume comparison or longer-term price series that would establish a breakout.
That leaves a narrower, supportable conclusion: Discovery traded slightly higher while receiving a substantial target-price increase.
This distinction does not diminish the relevance of the analyst revision. It makes the investment story more precise by separating what changed in market pricing from what changed in expectations.
The Developments Supporting Investor Interest
Several elements underpin the growth discussion:
- Revised broker valuation: BMO’s C$15 target provides a higher benchmark while leaving its recommendation unchanged.
- Exploration progress: The reference describes positive drilling results across key growth projects.
- Resource milestones: Dome and TVZ estimates were described as on track for late 2026.
- Portfolio expansion: Porcupine and Kidd Operations broaden Discovery’s operating and development opportunities around Timmins.
These developments do not carry identical financial significance. Drilling can improve geological understanding, while acquisitions add assets and responsibilities. Their eventual value depends on execution.
Why Are Dome and TVZ Important to Discovery Mining’s Growth?
The anticipated resource estimates are important because they could give investors a clearer basis for assessing the scale and confidence of mineralisation.
A drill result answers a limited geological question. A resource estimate brings multiple observations together, although it still does not establish that every identified ounce can be mined profitably.
Discovery’s Porcupine operations overview identifies Dome and the TVZ zone among its growth opportunities.
For the Discovery Mining stock surge thesis, the useful question is what the forthcoming estimates change. Additional ounces, improved confidence and a clearer development pathway have different implications.
The late-2026 timetable is an expected milestone, rather than confirmation that the estimates have already been delivered.
Acquisitions Expand the Opportunity and the Workload
Discovery’s Porcupine Complex and Kidd Operations acquisitions add another dimension to the story.
An enlarged operating base can provide more opportunities to coordinate assets and pursue growth. It also requires management to make decisions about investment priorities, operating performance and integration.
The company’s Kidd Operations description outlines the mining and processing infrastructure associated with that business.
For shareholders, ownership is the starting point. The commercial test is whether the assets contribute to a coherent operating plan and generate returns after the necessary expenditure.
A larger portfolio alone does not establish stronger per-share value.
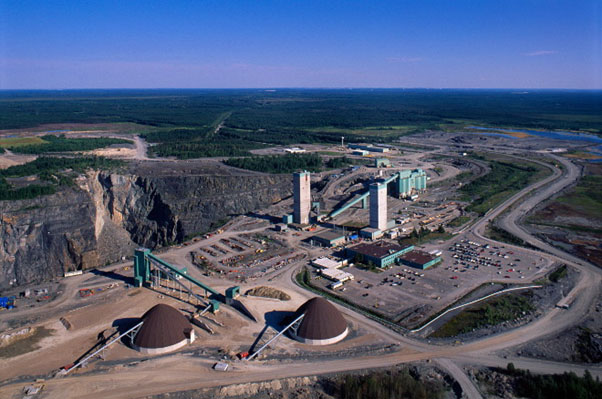
Figure 2: Archival photograph of Kidd Mine near Timmins, Ontario. Image source: Northern Ontario Business.
Questions the Broker Revision Does Not Answer
The higher target leaves several matters for investors to examine:
- Valuation assumptions: The supplied article does not reproduce BMO’s model or identify every assumption behind the revision.
- Development spending: It does not quantify the full capital required to realise the opportunities discussed.
- Operating delivery: It provides no new production-cost forecast against which to assess future performance.
- Consensus composition: Its claim of seven unanimous buy recommendations sits uneasily beside BMO’s retained market perform rating.
The last point may reflect different coverage universes or update timings. Without clarification, the consensus claim should not be treated as proof that every covering analyst recommends buying.
How Is the Gold Market Supporting Mining Stocks?
Company developments were not the only influence on sentiment.
The supplied report describes a gold rebound of more than 2% in the preceding session and a gain of more than 1% in the S&P/TSX Composite on September 17.
It also identifies retreating Treasury yields and oil prices as part of that recovery, following the Federal Reserve’s rate increase.
That backdrop helps explain why precious-metals equities attracted attention. However, it does not establish how much of Discovery’s modest September 18 gain came from BMO’s revision rather than broader market conditions.
The company-specific and sector explanations can coexist without being precisely measurable.
Turning Analyst Expectations Into Evidence
The analysts growth outlook mining discussion ultimately comes down to whether company results support the assumptions embedded in valuations.
An analyst can revise a target before a project delivers additional production. Markets routinely price future possibilities, but those possibilities remain exposed to changes in costs, schedules and commodity prices.
For Discovery, the next resource updates could sharpen the geological picture. Operating disclosures could then help investors assess how the enlarged portfolio is performing.
That sequence matters more than treating C$15 as a destination the share price must reach.
Milestones That Could Strengthen the Case
The next round of disclosures should be assessed against specific questions:
- Resource delivery: Are the Dome and TVZ estimates released within the indicated period?
- Geological confidence: What changes in classification, scale or interpretation?
- Development requirements: What further studies and expenditure are needed?
- Operational performance: Are acquired assets delivering against disclosed plans?
- Broker explanations: Do subsequent revisions explain changes to earnings or valuation assumptions?
These measures connect the growth narrative with evidence. They also make it easier to distinguish progress from a favourable change in sentiment.
What Should Investors Watch Next for Discovery Mining?
Discovery’s immediate news was a 25% increase in BMO’s target, accompanied by a small reported share-price gain.
The longer-term story concerns resource definition and the delivery of value from its expanded asset base. Those developments could influence future valuations, but their outcomes remain uncertain.
Investors therefore have a clear set of milestones to follow, rather than a confirmed surge or verified proximity to a trading high.
FAQ
Did BMO upgrade its recommendation?
No. It retained market perform.
Was the share price up 25%?
No. The target increased 25%; the reported share-price gain was 0.1%.
Is the C$15 target guaranteed?
No. It is an analyst valuation estimate.
Also Read: ASX Mining Stocks Slide as Rate Hike Fears and Oil Surge Pressure the Resource Sector
Disclaimer
Prepared for Mining Herald for general information, not investment advice. Analyst targets, resource expectations and development plans may change. Quoted prices reflect historical reporting. Readers should independently review company disclosures and current market information before making investment decisions.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.