Key Takeaways
- 01 Capital discipline is reshaping commodity supply curves into 2026.
- 02 AI infrastructure capex is becoming a primary macro variable.
- 03 Central bank policy across AU, CA and US is converging on neutral.
The global economy market repricing left investors with mixed results on 2 Oct 2026. US shares rose after weaker employment figures reduced expectations of an immediate rate increase. Bonds initially found support, but selling returned later in the session.
That leaves a practical question for resource companies: what will their next round of funding cost?
An operating mine may be able to pay for work from its cash receipts. An explorer usually has to look elsewhere. Both can benefit from investor interest in commodities, but their ability to fund the next year of work may differ considerably.
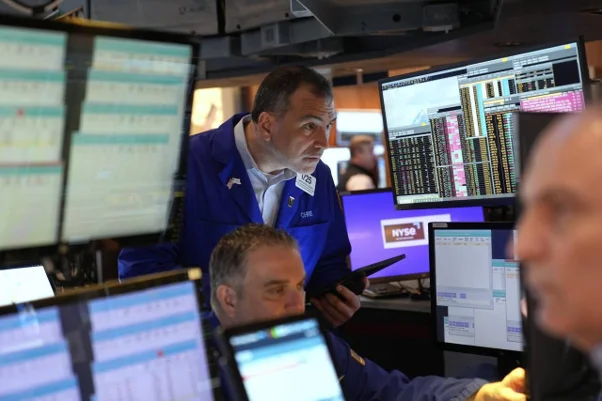
Figure 1: Trading activity on the New York Stock Exchange as investors reassess equities and bond yields amid changing economic expectations. Credit: Reuters
Three Funding Positions Produce Different Outcomes
- A producer with surplus cash may fund planned work without approaching lenders or shareholders.
- A company with debt coming due must find the cash to repay it or agree on replacement funding.
- An explorer may need another share issue before drilling can continue.
- A developer must establish whether the money available will cover construction and the period before revenue begins.
These differences can be missed when an entire sector rises or falls together.
Mining Herald’s report on the commodities crunch facing ASX mining stocks looks at the pressure from borrowing costs, commodity prices and mine expenses.
Bond Yields Matter When Companies Return for Money
Companies do not all pay more interest as soon as government bond yields rise. A borrower with an existing fixed-rate loan may retain those terms until maturity.
The change becomes more immediate when that company needs new money.
Lenders consider the borrower’s finances and the risk of the proposed work. Government bond yields provide a benchmark, with additional borrowing costs depending on the company and the loan.
A project assessed under earlier funding assumptions may therefore need another review. Its deposit has not changed. The amount required to finance development, and the return left after financing expenses, may have.
The Economic Forecast Still Points to Growth
The IMF’s July outlook put global growth at 3.0% for 2026 and 3.4% for 2027. It also said the decline in global inflation had stalled.
The report described an uneven outlook. Technology demand was helping some economies, while energy costs were weighing on others. Both annual growth figures were forecasts.
Continued growth gives commodity producers a basis for demand. It says less about the outlook for an individual shipment of copper, iron ore or gold.
Buyers may already hold enough stock. New supply may reach the market. A shortage in one commodity can exist alongside excess material in another.
Key Figures Behind the Outlook
| Item | Reported figure | Period |
| IMF global growth forecast | 3.0% | 2026 |
| IMF global growth forecast | 3.4% | 2027 |
| World Bank commodity-price forecast | 16% increase | 2026 annual change |
| World Bank energy-price forecast | 24% increase | 2026 annual change |
The World Bank figures come from its April outlook. They describe expected annual changes, rather than returns recorded so far this year.
A Higher Selling Price Does Not Settle the Mine’s Result
For a producer, the first question is how much saleable material leaves the operation. The next is what the company receives for it.
Costs then determine how much cash remains.
Diesel, electricity and freight can become more expensive during a commodity upswing. If a mine produces less than planned, fixed expenses must also be spread across fewer units of output.
This is where the equities bonds commodities shift reaches company accounts. The market may value the shares more highly while the operation faces a larger bill.
Contracts matter here. Some businesses have fixed part of their energy costs or agreed prices for part of their production. Their exposure can differ from a company buying and selling at current market rates.
Gold Companies Have Their Own Numbers to Meet
A gold-price rise can improve expected revenue. It cannot tell readers whether a particular mine has met its production target.
Grades, recovery rates and maintenance work all affect output. Spending on replacement equipment or mine development may also use cash that would otherwise remain on the balance sheet.
There is a further distinction between owning gold and holding shares in a gold company. The shareholder takes on the company’s operating and funding risks.
Mining Herald’s coverage of gold price momentum and interest-rate pressure examines the market conditions surrounding bullion.
US Share-Market Snapshot
| Index | Close, 2 Oct 2026 | Daily movement |
| S&P 500 | 7,722.72 | +0.7% |
| Dow Jones Industrial Average | 51,176.96 | +0.5% |
| Nasdaq Composite | 27,190.86 | +1.2% |
| Russell 2000 | 2,832.90 | +0.9% |
These are closing figures for the stated date, rather than live quotes.
Cash Requirements Set the Next Checkpoints
Mining Herald’s assessment is that the next company reports will be more useful than a single day’s share-price movement.
For producers, the checks are output, costs and cash generated from operations. For developers, they include construction estimates and the funding still to be secured. Explorers need enough cash to complete the work they have announced.
Readers should also compare new guidance with the previous estimate. An unchanged production target means less if the expected cost of achieving it has risen.
The next stage of global investment market changes will become clearer as those figures arrive. Until then, higher commodity prices alone do not establish which companies will finish the period with more cash.
ALSO READ: ASX Mining Stocks Slide as Rate Hike Fears Hit Market
FAQs
Q1. What happened in markets on 2 Oct 2026?
Ans. US stocks rise on weaker employment data. Earlier improvement gave way to selling of bonds.
Q2. Why are the mining companies worried about rising bond yields?
Ans. They can influence the cost of new loans. It is contingent upon when a company needs the money and the terms it can get.
Q3. Do higher commodity prices mean higher profits for miners?
Ans. Not so much. Higher costs and production shortfalls can nibble away at more revenue.
Q4. What should readers expect from company updates?
Ans. Cash balances, debt repayments, production results, cost guidance and funds required for planned work.
Disclaimer
The following material is for educational use only. Figures and forecasts are from third party sources and are as of the dates stated. Please consult the market data and filings of the companies mentioned before making any investment decisions. Investments are subject to risk of loss. The contents of this piece are not financial advice.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.