Key Takeaways
- 01 Capital discipline is reshaping commodity supply curves into 2026.
- 02 AI infrastructure capex is becoming a primary macro variable.
- 03 Central bank policy across AU, CA and US is converging on neutral.
James Hardie Industries plc (ASX: JHX) has been getting attention again. It is a well known company in the S&P/ASX 200 Index (ASX: XJO). Wilson Asset Management has now noted it as one of the better picks in the WAM Leaders Ltd (ASX: WLE) portfolio.
That is not a small call, given how many building products names the fund runs its eye over. It comes as the Company posts a genuine profit surge, ASX 200 stock investors have been quietly tracking for months.
Figure 1: James Hardie siding products stacked outside a manufacturing facility [Courtesy: Reuters]
James Hardie sits at the centre of two big stories right now. One is a fresh push into ASX 200 global expansion stocks territory through a major European sale. The other is a stronger-than-expected quarterly result that pushed full-year guidance higher. Put those together, and it is not hard to see why experts keep circling this ASX 200 blue-chip, top buy candidate.
What Makes This ASX 200 Blue Chip Top Buy So Compelling Right Now
James Hardie describes itself as the industry leader in exterior home and outdoor living solutions. Its portfolio spans fibre cement, fibre gypsum, and composite and PVC decking and railing products. The Company already trades across North America, Europe, Australia and New Zealand.
That scale did not happen overnight. James Hardie built this footprint through steady product innovation and market share gains over many years. It is exactly why fund managers keep treating it as an ASX 200 blue-chip top buy. Few local building product names carry this level of international reach.
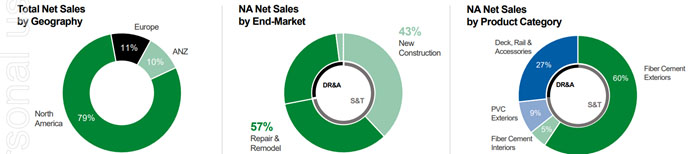
Figure 2: James Hardie’s global sales mix by geography and product [Courtesy: James Hardie Industries plc]
Snapshot of James Hardie’s global position:
- Fibre cement, fibre gypsum, composite and PVC decking products
- Operations across North America, Europe, Australia and New Zealand
- Held as a core position inside WAM Leaders Ltd (ASX: WLE)
- Delivering above-market growth despite a subdued US housing market
European Exit Fuels a Fresh ASX 200 Global Expansion Stocks Story
James Hardie has just announced it is planning to sell its European operations. The sale includes Fermacell, which will go to Holcim for €840 million.
The rationale is straightforward. Proceeds will accelerate deleveraging and return capital to shareholders, James Hardie confirmed. The Company also intends to close its European fibre cement business, subject to legal, regulatory and employee consultation requirements, including works council input.
Investors chasing ASX 200 global expansion stocks are watching this reshuffle closely, since it effectively narrows James Hardie’s global footprint to sharpen its highest-growth markets.
A Genuine Profit Surge ASX 200 Stock Investors Are Watching
James Hardie said its 1Q FY27 numbers looked strong for the period that ended 30 Jun 2026. Net sales came in at US$1.475 billion. That was up 64% from the same quarter last year. Net income was US$104 million. Adjusted EBITDA reached US$422 million.
CEO Aaron Erter said the Company delivered sales and adjusted EBITDA ahead of our original guidance, driven by double-digit sell-through in Siding & Trim.
Q1 FY27 segment snapshot:
| Segment | Net Sales | YoY Change | Adjusted EBITDA / Margin |
| Siding & Trim | US$860 million | +34% reported, +20% organic | — |
| Deck, Rail & Accessories | US$305 million | -5% pro forma | US$83 million (~27% margin) |
| Australia & New Zealand | – | +26% (+14% in AUD) | 34.9% margin |
| Europe | – | +15% (+12% in EUR) | 19.4% margin |
The North American fibre cement business returned to volume growth on the back of continued market share gains. That turnaround is a big reason the Company raised guidance, and why the profit surge ASX 200 stock story is getting louder.
FY27 full year guidance:
| Metric | Guidance Range |
| Total Net Sales | US$5.564 billion to US$5.723 billion |
| Total Adjusted EBITDA | US$1.536 billion to US$1.625 billion |
| Free Cash Flow | At least US$500 million |
What Experts Like About James Hardie Shares
James Hardie remains a core holding inside the WAM Leaders investment portfolio. Wilson Asset Management said the Company continues to deliver above-market growth, and it credits strong execution of cost and commercial synergies for that.
There is also the balance sheet angle. James Hardie’s European divestment lets management sharpen its focus on core growth markets, and WAM said this should support further deleveraging.

Figure 3: James Hardie’s cost and commercial synergy progress [Courtesy: James Hardie Industries plc]
Market share gains have persisted even with a subdued US housing market sitting in the background, which is nothing. Experts continue to view this ASX 200 blue chip top buy as a core portfolio holding rather than a short-term trade.
Industry Outlook
Australia’s building materials market is not standing still. The market was valued at US$26,928.6 million in 2025 and is projected to reach US$38,769.6 million by 2034. This translates into a CAGR of 4.13% between 2026 and 2034.
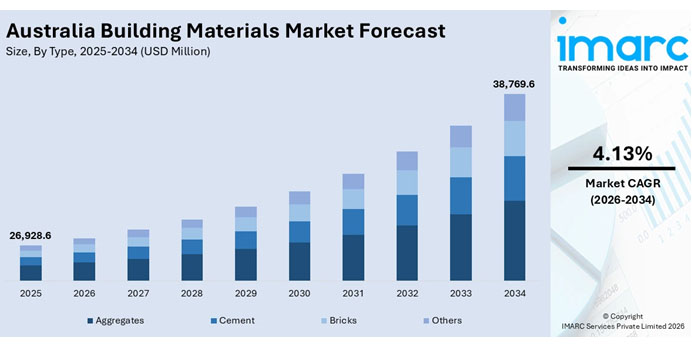
Figure 4: Australia building materials market forecast by type, 2025 to 2034 [Courtesy: IMARC Group]
Sustainable materials are becoming more mainstream across the sector. Recycled wood, eco-concrete, and renewable insulation are starting to show up in regular projects. Tighter rules on emissions and waste are one reason why this shift is happening.
People also want faster build times and easier site work. That is why prefabrication and modular jobs are growing. Many now use light steel frames and modular concrete panels because they fit together more neatly than older methods. Digital tools are changing the picture as well, since Building Information Modelling and AI-based design platforms are reshaping how materials get selected and specified.
Share Price Snapshot
| Metric | Value |
| Last price | A$41.99 per share |
| Bid/offer range | A$41.98 to A$41.99 per share |
| 52-week range | A$24.41 to A$44.12 per share |
| 1 week performance | +1.18% |
| 1 month performance | +2.67% |
| 2026 year-to-date | +35.72% |
| 1-year performance | +40.03% |
| Versus the ASX 200 over 1 year | +38.48% |

Figure 5: James Hardie share price movement over the past year [Courtesy: James Hardie Industries plc]
Future Direction: Impact on ASX 200 Investors
James Hardie’s next milestones are already taking shape. The Company expects to complete its European exit in conjunction with continued deleveraging through FY27. In addition, management will present its long-term strategy at its Investor Day in New York City in September 2026.
For readers tracking ASX 200 global expansion stocks, this timeline matters. A leaner global footprint combined with rising guidance strengthens the case for this profit-surge ASX 200 stock.
That combination keeps James Hardie firmly on the radar as an ASX 200 blue-chip top buy heading into next year, at least according to the fund managers who have already put their money where their conviction is.
Readers following the ASX 200 blue-chip top buy conversation can find ongoing coverage of building materials and industrial stocks on Mining Herald.
ALSO READ: Gold Faces Weekly Decline After Strong US Labor Data Strengthens Dollar Outlook
FAQ
Q1. Where does James Hardie’s fibre cement business operate?
Ans. James Hardie’s fibre cement operations span North America and Australia & New Zealand, with its European fibre cement business now set to close.
Q2. Why is James Hardie selling its European operations?
Ans. Proceeds will accelerate deleveraging and return capital to shareholders.
Q3. What did WAM Leaders say about James Hardie?
Ans. WAM called it one of its most compelling holdings, citing above-market growth.
Q4. What is James Hardie’s FY27 net sales guidance?
Ans. Guidance sits between US$5.564 billion and US$5.723 billion.
Q5. What is driving this profit surge ASX 200 stock story right now?
Ans. Stronger North American volumes and synergy gains are driving it.
Disclaimer
This article is intended for informational purposes only. If you pay attention to the ASX 200 and building materials sector as an investor, all data in this content is from third-party sources. Please check out the complete share price and market data info. Investing carries a high risk, and you should only invest at your own risk. Mining Herald has no involvement in the above-listed company.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.