Key Takeaways
- 01 Genesis produced 72,107 ounces in the September quarter at an all-in sustaining cost of AUD 2,966 an ounce.
- 02 The Vault merger scheme became legally effective on 17 November 2026. Implementation is expected on 26 November.
- 03 The proposed combined portfolio offers processing savings, but the approximately AUD 2 billion synergy estimate is not cash already earned.
For Genesis Minerals ASX investors, the next stage involves more than adding another set of mines. Existing operations must keep paying their way while the company develops new ore sources and brings two portfolios together. In this article, Mining Herald examines the cash available, the spending ahead and the operating decisions that will shape whether expansion produces a stronger business.
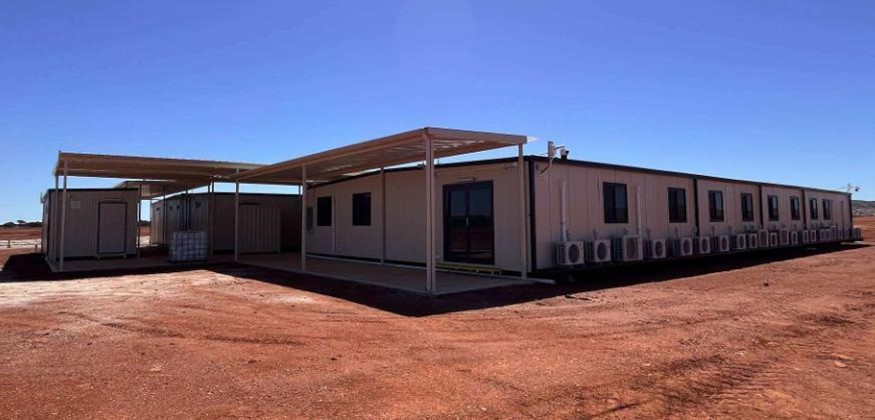
Figure 1: Offices at Genesis Minerals’ Tower Hill development, pictured in its September 2026 quarterly report. Credit: Genesis Minerals Limited.
Operating Cash Gives Genesis a Starting Point for Expansion
Genesis sold 71,594 ounces during the September quarter at an average realised price of AUD 5,902 an ounce. Those deliveries generated AUD 422.5 million in revenue.
The mine operating cash flow figure was AUD 213 million. After AUD 51 million of growth capital, net mine cash flow was AUD 162 million. These measures help explain how the company could fund development and still increase its cash balance.
They do not describe money available without further claims on it. Genesis also had exploration, corporate, tax and transaction commitments. The company’s bank debt stood at AUD 200 million, leaving net cash of AUD 398 million at the quarter end.
A Larger Cash Balance Must Be Read Against the Bills Ahead
| September 2026 Measure | Reported Result |
| Gold produced | 72,107 ounces |
| All-in sustaining cost | AUD 2,966 per ounce |
| Revenue | AUD 422.5 million |
| Cash and equivalents | AUD 598.0 million |
| Bank debt | AUD 200 million |
| Net cash | AUD 398.0 million |
The quarter closed before Genesis paid its maiden dividend on 5 October. That payment used approximately AUD 59 million. The company also anticipated an FY2026 tax catch-up payment of AUD 100 million to AUD 120 million during the December quarter.
Those obligations matter when assessing the Genesis Minerals growth outlook. September cash cannot simply be carried forward unchanged into a construction funding calculation.
Underlying cash generation of AUD 157.4 million was below the June quarter’s AUD 263.8 million. Genesis still added cash, but the pace changed. Mining Herald’s coverage of Genesis’ gold production and cost trends provides a closer look at the operating quarter.
Shared Processing Could Remove a Major Construction Requirement
The most concrete merger benefit is the chance to use a larger network of mills and ore sources. Genesis’ standalone FY2027 growth capital guidance of AUD 380 million to AUD 420 million included AUD 140 million for a new Tower Hill mill. Its quarterly report said the Vault merger would remove the need for that mill.
Avoiding a new plant can reduce the capital required before ore generates revenue. The alternative still has to work: ore must reach a suitable mill, available capacity must match the mining schedule, and processing costs must justify the arrangement.
Management has identified approximately AUD 2 billion of potential post-tax, undiscounted synergies. That is an estimate across future periods. It is neither an annual profit forecast nor AUD 2 billion sitting in the bank.
New Ore Sources Need to Arrive on the Mine Schedule
Two Genesis Minerals gold projects have nearer operating milestones. Bruno Lewis was targeting first ore in the December 2026 quarter. Tower Hill was targeting first ore in FY2028, with early mining ahead of schedule when the September report was released.
First ore is a useful checkpoint, but it does not establish a mine’s sustained contribution. Shareholders will need to see tonnes delivered, grades achieved, processing recovery and the cost of producing saleable gold.
Existing mines also show why output cannot be judged from tonnes alone. Gwalia mined more ore in September than in June, but its lower grade reduced contained gold. At Ulysses, stronger ore delivery and grade lifted contained gold to a record 17,400 ounces. Those are mining figures, not separate company gold sales.
The Merger Timetable Is Further Advanced Than the Operating Savings
Vault confirmed on 17 November that the scheme had become legally effective after the court orders were lodged with ASIC. Implementation and payment of scheme consideration are expected on 26 November.
Legal effectiveness clears an important step. Integrating mine plans, capital budgets and processing schedules takes longer. Genesis is targeting the June quarter of 2027 for a combined long-term strategic plan, including multi-year production and cost assumptions.
Until that plan arrives, the standalone FY2027 production guidance of 270,000 to 300,000 ounces should not be mistaken for guidance covering the enlarged company.
A Stronger Business Must Justify the Price Investors Pay
The valuation comparison supplied for this article put Genesis on approximately 12.8 times earnings, above both its cited sector and peer averages. That snapshot does not establish that the stock is expensive or cheap. The earnings used, gold price assumptions and merger treatment all affect the comparison.
A buyer expecting savings needs to check what has actually changed:
- Capital avoided: Does the revised plan remove the Tower Hill mill expenditure, and what replacement work is required?
- Operating delivery: Do new ore sources improve mill utilisation and costs without creating extra transport or processing problems?
- Cash retained: How much remains after growth spending, tax, dividends and merger costs?
Genesis has profitable operations and a substantial cash position to support the next stage. The case for a stronger business rests on converting the enlarged portfolio into lower spending requirements and dependable cash generation. The combined strategic plan should make that proposition easier to test.
ALSO READ: Australia’s Next Gold Mines: Projects Moving Closer to Commercial Production
FAQs
Has the Vault Merger Been Implemented?
As at 19 November 2026, the scheme is legally effective. Implementation is expected on 26 November.
Is the AUD 2 Billion Synergy Figure an Annual Saving?
No. It is an estimated post-tax, undiscounted total of potential synergies over future periods.
Does the AUD 598 Million Cash Figure Include Debt?
It is the cash balance. Deducting AUD 200 million of bank debt gives September net cash of AUD 398 million.
When Will Genesis Publish Its Combined Strategy?
The company is targeting the June quarter of 2027 for a long-term plan covering the Genesis and Vault portfolio.
Disclaimer: This article provides general information, not personal financial advice. Figures and transaction status reflect disclosures available on 19 November 2026. Production targets, potential savings and project dates are estimates. Share prices and gold prices can move, and forecast benefits may not be realised.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.