Key Takeaways
- 01 Vickery’s scope, capital and funding are under review. Winchester South awaits further external approvals after a Queensland Land Court recommendation.
- 02 Investment decisions will follow market conditions and return hurdles, not a fixed timetable.
- 03 Early FY27 coal prices sit above FY26 averages, which improves the funding backdrop.
Whitehaven Coal Limited (ASX: WHC) leveraged its 2026 Annual General Meeting on 5 November 2026 to discuss and clarify its thinking to shareholders concerning two growth opportunities.
Paul Flynn, MD and CEO, commented that final decisions concerning the growth projects and the associated capital will reflect market conditions and capital allocation priorities. The Vickery Extension Project in New South Wales and the Winchester South Project in Queensland drew the focus.
Vickery Extension Is Under Review While Winchester South Gains Approval Momentum
- The Whitehaven Coal Vickery project is in New South Wales. Work is underway to review its scope, capital requirements and funding options.
- The Winchester South coal project is in Queensland. It is still moving through external approvals. The Queensland Land Court recently recommended approval, which Flynn described as real progress.
- Flynn said both developments could add significant shareholder value. He said they continue to draw strong customer support.
Strict Return Hurdles Decide When Either Development Gets Capital
Whitehaven runs a capital allocation framework with four priorities. Focusing on operations and balance sheet health comes first, followed by providing returns to shareholders. Any excess capital will fund additional returns, as well as development of organic growth opportunities and acquisitions.
For organic growth, the Company advances development projects until they are shovel-ready. It invests only when returns are compelling and minimum internal rate of return hurdles are met.
FY26 Cash Flow and a Refinanced Debt Stack Frame the Funding Picture
Whitehaven reported the results below despite coal prices sitting well below recent highs.
| Measure | Year ended 30 Jun 2026 |
|---|---|
| Revenue | A$5.4 billion |
| Underlying EBITDA | A$1.3 billion |
| Underlying net profit after tax | A$227 million |
| Operating cash flow | Approximately A$1.1 billion |
| Net debt | Approximately A$1.3 billion |
| Liquidity | Approaching A$1.0 billion |
The Company performed a refinancing of the acquisition debt during May 2026. This offering was done via a US$900M heavily oversubscribed debt placement, being approximately 12x the size. In addition, there is a US$600M senior secured syndicated bank facility. Whitehaven expects annualised interest savings of around A$50M to A$55M due to the new financing.
Early FY27 Coal Prices Improve the Backdrop for Growth Spending
Whitehaven said that both thermal and coking coal pricing are stronger and that these coal price increases support greater earnings.
| Measure | FY26 average | Q1 FY27 average |
|---|---|---|
| PLV HCC (metallurgical) | US$214 per tonne | US$248 per tonne |
| gC NEWC (thermal) | US$118 per tonne | US$135 per tonne |
| AUD: USD | 0.68 | 0.71 |
A stronger Australian dollar works against those gains. The Company said adverse exchange rate movements persist. FY27 total capital expenditure guidance is A$390 million to A$490 million, excluding M&A, versus A$349 million in FY26. The announcement does not split that range by project.
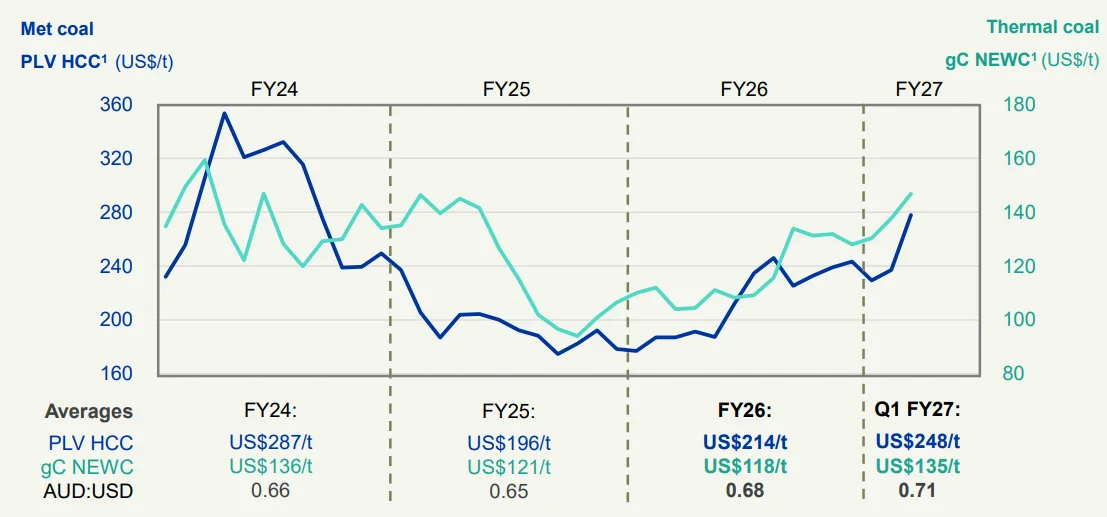
Figure 1: Metallurgical and thermal coal price averages by financial year, including Q1 FY27. [Courtesy: Whitehaven Coal Limited]
Approvals, Costs and Operations Could Delay or Reshape Investment
- Achieved coal prices fell 6% in FY26 on softer markets and adverse exchange rates.
- Whitehaven uses about 340 million litres of diesel a year. Higher diesel prices added more than A$40 million to costs late in FY26.
- Winchester South still needs external approvals. Vickery’s capital and funding options remain under review.
- Challenging conditions at Narrabri limited second-half FY26 production. A nine-week longwall move is scheduled for the second half of FY27.
Industry Outlook: Seaborne Coal Supply Gaps Are Forecast Towards 2050
Commodity Insights, an external forecaster cited by the Company, expects a seaborne metallurgical coal shortfall of 162 million tonnes per annum by 2050. It forecasts a 118 million tonnes per annum gap in high-CV seaborne thermal coal. The Company attributes the gaps to ageing mines and a thin pipeline of new supply.
Whitehaven Shares Trade Inside Their 52 Week Range
| Measure | Data |
|---|---|
| Last price | A$7.235 per share |
| Market capitalisation | A$6.01 billion |
| 52-week range | A$6.660 to A$9.900 |
| Total Shareholder Return, 12 months to 30 Jun 2026 | 41% (17th in the ASX 100) |
| Total Shareholder Return, five years to 30 Jun 2026 | 448% (top five in the ASX 100) |
Impact on Queensland Cash Flow and Growth Funding Once BMA Payments End
Confirmed next steps are limited. Vickery’s scope, capital and funding review continues, and Winchester South still needs external approvals. The announcement gives no decision dates.
The nearer cash flow event is the BMA contingent payment. The three-year payment period ends in Apr 2027, and the final payment is due in Jul 2027, capped at US$350 million. Based on current forward prices, the Company expects it to be materially higher than the earlier payments of US$9 million and US$58 million. Once the vendor finance is repaid, Whitehaven keeps the full benefit of Queensland cash flows.
Mining Herald will track both projects as the Company reports further progress.
FAQs
Q1: Which development projects does Whitehaven highlight?
Ans: The Vickery Extension Project in New South Wales and the Winchester South Project in Queensland.
Q2: Has Whitehaven announced final investment decisions?
Ans: The AGM addresses did not announce a decision for either project. Timing will reflect market conditions, capital priorities, and return hurdles.
Q3: What is the latest Winchester South milestone?
Ans: The Queensland Land Court recommended approval. External approvals are still progressing.
Q4: What shareholder payout does the Company target?
Ans: Between 40% and 60% of underlying net profit after tax, through fully franked dividends and buy-backs.
Disclaimer
This article is intended for informational purposes only. If you pay attention to the coal sector as an investor, then all the data in the content is from third-party sources. Please check out the complete share price and market data info. Investing carries a high risk, and you should only invest at your own risk. Mining Herald has no involvement in the above-listed company.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.