Key Takeaways
- 01 Aspect brings plant design and minerals processing expertise to a contractor known for surface mining, underground mining and civil works.
- 02 Of the A$75 million base-case price, A$30 million was payable at completion. The remaining balance depends on retention and performance over several years.
- 03 The two teams have started working together. Macmahon’s completion announcement did not name a new contract they had won together.
Macmahon Holdings confirmed on 2 November 2026 that it had completed its acquisition of Aspect Engineering Solutions and its subsidiaries. In this article, Mining Herald looks at the work behind those earnings, why it fits Macmahon’s business and what the buyer has agreed to pay.
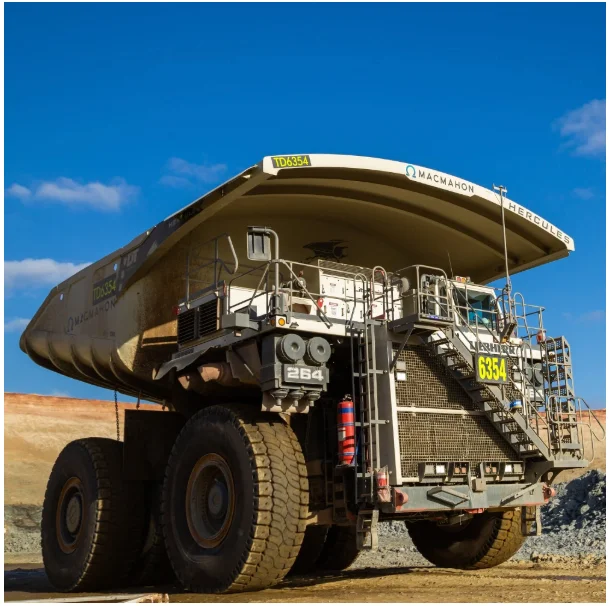 Figure 1: Surface mining at Tropicana. Macmahon’s purchase of Aspect adds minerals processing and engineering design to its existing contracting business. Archive photograph. Credit: Macmahon Holdings Limited.
Aspect Can Help Decide What Gets Built
Take a proposed expansion at an operating mine. The mining team may know how quickly it can deliver more ore.
The owner still needs to establish whether the processing plant can handle that ore, which equipment needs replacing and how long the plant would have to stop for installation. A few extra days of lost production could change the choice of design.
Aspect can take on the feasibility work and detailed engineering. If the owner approves the project, Macmahon can also tender for construction and mining. Once the plant is running, the group can offer operations and maintenance support. The owner may award those jobs separately, but Macmahon now has a reason to speak to the client before the construction tender goes out.
An Existing Mine May Be the First Customer
Macmahon does not need to wait for a new mine to open to put Aspect’s mining engineering services to use. An existing client may already have work for both businesses.
An engineer would first need to establish where the plant is losing metal and whether changing the process would earn enough to cover the cost. Mining Herald’s guide to leaching-tank performance and metal recovery looks at one part of that problem.
The opportunity also runs the other way. An Aspect customer that knows the engineering team through a plant study could consider Macmahon for work on site.
Aspect co-founder and managing director Justin Giblett identified the two firms’ different client bases as one reason for bringing them together. Neither company put a dollar figure on the work those introductions might generate.
What the A$75 Million Price Actually Covers
Revenue is what Aspect earned from customers before expenses. The more useful figure for judging the price is its roughly A$15 million in unaudited earnings before interest and tax (EBIT). On that basis, the headline valuation was about five times annual EBIT.
| Part of the deal | Amount | Payment terms |
| Cash at completion | A$30 million | Subject to a customary net working-capital adjustment |
| Retention payments | A$30 million | A$6 million a year for five years, subject to retention conditions |
The five-year retention period says something about what Macmahon is buying. Drawings and equipment specifications can change hands on completion day.
The people who remember why a client rejected an earlier design, or how much downtime a particular site can tolerate, are harder to replace.
What Shareholders Can Check in the Next Results
Macmahon announced the proposed deal on 18 September. On 20 October, the Australian Competition and Consumer Commission issued a waiver confirming that the acquisition did not require notification. By 2 November, Macmahon had confirmed that the remaining conditions had been met.
Management expects Aspect to lift underlying earnings per share by approximately 6.2% from the outset, before counting any additional benefit from combining the businesses. That forecast gives shareholders a starting point: Macmahon expects the acquired business to contribute earnings even before the two teams win extra work together.
For readers comparing the mining engineering companies Australia has to offer, there are two separate questions here. Can Aspect sustain the earnings Macmahon paid for? And can the two businesses win work that neither would have secured alone?
The November announcement answers neither yet. A named job that starts with an Aspect feasibility study and goes on to include a Macmahon construction or maintenance contract would offer the clearest evidence that the purchase is changing the business.
For a mine owner’s view of the work between a development decision and first production, see Mining Herald’s report on the Prieska copper revival.
ALSO READ: Sandfire Resources Q1 FY27: Copper Output and Growth Outlook
FAQs
Q1. What can Macmahon offer clients after buying Aspect?
It can help a mine owner compare project options, design a processing facility and plan how to operate it. Those services sit alongside Macmahon’s mining and civil contracting work.
Q2. Did Macmahon pay A$75 million upfront?
The purchase price was A$30 million cash on completion subject to adjustment. Additional payments are based on retention and performance.
Q3. Was Aspect profitable before the acquisition?
Aspect reported approximately A$15 million in FY26 EBIT on revenue of about A$75 million. Both figures were unaudited. The announcement did not provide a net profit figure.
Q4. Has the deal already lifted earnings per share by 6.2%?
That was Macmahon’s estimate for underlying earnings per share before any benefits from combining the businesses. It was not a reported post-acquisition result.
Disclaimer
This article provides general information, not personal financial advice. Aspect’s FY26 figures are unaudited. Actual earnings and final acquisition payments may differ from the estimates.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.