Key Takeaways
- 01 Westgold Resources produced a record 387koz in FY26 and outlines 460koz to 510koz for FY29.
- 02 Processing capacity is planned to rise from 5.7Mtpa to above 7Mtpa through Cue and Meekatharra expansions.
- 03 Treasury of A$1,040 million funds growth and an A$50 million FY27 buy-back.
Westgold Resources Limited (ASX: WGX) has stopped talking turnaround and started talking growth. Its corporate update dated 11 Nov 2026 lays out the plan. It needs more ounces and more mill capacity. It does not need a lender.
The Westgold Resources production forecast now runs to FY29.
Record FY26 Output and a Steady Start to FY27 Set the Base
Westgold Resources gold production reached a record 387 thousand ounces (koz) in FY26. That topped the Company’s own guidance. A year earlier, it was 326koz.
The September quarter added 98.4koz. Costs came in at A$2,912 per ounce on an all-in sustaining cost (AISC) basis, under the FY27 guidance range. That held up despite heavier maintenance and wet weather in the Murchison. High-grade stockpiles climbed to 696 thousand tonnes, built on purpose.
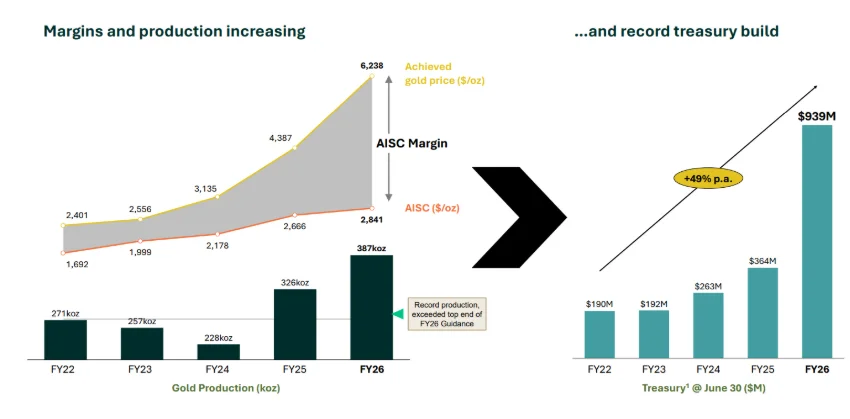
Figure 1: Westgold’s production, achieved gold price and cost trend from FY22 to FY26. [Courtesy: Westgold Resources]
The Three-Year Outlook Lifts Output While Costs Ease
Under its three-year outlook dated 9 Sep 2026, the Westgold Resources FY29 production outlook is 460koz to 510koz. AISC is expected to ease to A$2,640 to A$3,000 per ounce by then.
| Period | Production (koz) | AISC (A$ per ounce) |
|---|---|---|
| FY26 (actual) | 387 | 2,841 |
| FY27 (guidance) | 385 to 425 | 2,980 to 3,380 |
| FY28 (outlook) | 425 to 470 | 3,000 to 3,400 |
| FY29 (outlook) | 460 to 510 | 2,640 to 3,000 |
FY27 looks like a holding year. Guidance of 385koz to 425koz sits near FY26’s 387koz. Guided AISC is higher too. The gains come later, with new capacity and better grades.
Part of the outlook rests on inferred resources. The Company says there is no certainty the target will be realised.
Cue and Meekatharra Expansions Drive the Capacity Lift
- The mills process 5.7 million tonnes per annum (Mtpa) today. The Company wants more than 7Mtpa by FY29.
- Cue expands first, with commissioning targeted in FY27. Meekatharra follows in FY28.
- Great Fingall is due to reach commercial production by the end of FY27.
- Murchison goes first. Southern Goldfields follows with Fletcher.
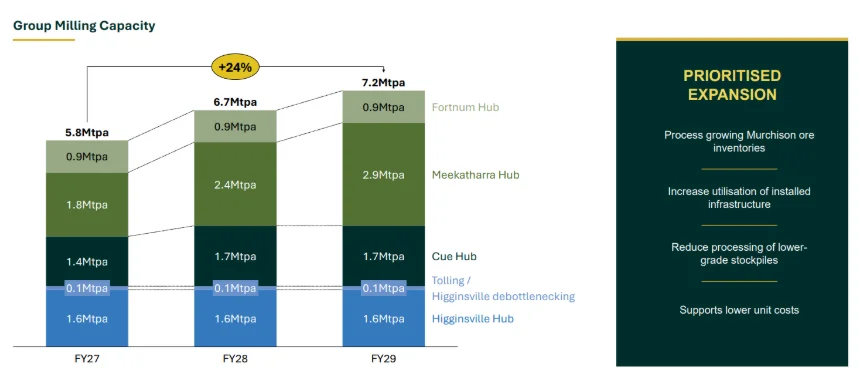
Figure 2: Planned growth in Westgold’s group milling capacity by hub through FY29. [Courtesy: Westgold Resources]
Beta Hunt Hits a Record Rate, and Fletcher Adds Upside
Beta Hunt hit an annualised 2Mtpa in Sep 2026, a record month. Under prior ownership, it ran at about 1.4Mtpa. The Company spent A$33.3 million over two years on ventilation, dewatering, water supply and power.
Holding that pace is the test. A sustained 2Mtpa rate is targeted in Q2 FY27. Fletcher could add about 140 thousand ounces a year. It sits outside the outlook, and the Company says it cannot yet show the target is achievable.
Ore Reserves Rise 41% to Extend the Runway
Ore Reserves now stand at 4.1 million ounces (Moz), up 41%. A maiden Fletcher Reserve of 1.1Moz is part of that. Beta Hunt has a 16-year reserve life, while Starlight has four.
Operating Cash Flow Funds Growth and Shareholder Returns
- Treasury was A$1,040 million at 30 Sep 2026, with no debt and no hedging.
- Available liquidity is A$1,640 million, including an undrawn A$600 million facility.
- Non-sustaining capital is guided at A$450 million to A$480 million in FY27. It eases to A$390 million to A$410 million by FY29.
- FY26 capital returns were A$122 million. An FY27 buy-back of A$50 million is underway.
Peer Valuation Gap Frames the Company’s Case
On FY27 estimates, the Company trades at 3.1x enterprise value to EBITDA. Capricorn Metals sits at 9.4x and Northern Star Resources at 8.1x. Only Regis Resources and Pantoro Gold are lower. The Company calls this a mispricing, but that argument rests on its own peer set.
Gold Price and Execution Risks Remain
Gold is the obvious risk. The Company also names exploration results and permitting. Delivery matters too, because Cue and Meekatharra must land on time. The Murchison already felt wet weather in Q1 FY27.
Industry Outlook: Wider Margins Have Powered Producer Cash Flow
Gold did the heavy lifting. The Company’s achieved price rose from A$2,401 per ounce in FY22 to A$6,238 in FY26. AISC moved from A$1,692 to A$2,841. Treasury grew from A$190 million to A$939 million. Those margins depend on gold holding up.
Share Price Strengthens Sharply Over One Week and One Month
Westgold Resources (ASX: WGX) trading data is below, as at 11 Nov 2026. The shares remain below their 52-week high.
| Metric | Data |
|---|---|
| Last price | A$5.93 per share |
| Market capitalisation | A$5.68 billion |
| 52-week range | A$4.24 to A$8.16 |
| 1 week change | +15.92% |
| 1 month change | +15.92% |
| 1-year change | +2.86% |
Scheduled Milestones From Q2 FY27 Will Test the Plan
The calendar is short and specific. Q2 FY27 is Beta Hunt at a sustained 2Mtpa. Q3 FY27 brings Southern Goldfields studies and half-year results. Q4 FY27 is when Cue commissioning and Great Fingall production are targeted.
For Westgold Resources gold production, the FY28 outlook of 425koz to 470koz is the next step. For capacity, Meekatharra takes the Company above 7Mtpa by FY29. For shareholders, the FY27 dividend is determined in Aug 2027.
Mining Herald will track each milestone as the Company reports it.
FAQs
Q1. What is the Westgold Resources FY29 production outlook?
Ans. 460koz to 510koz at an AISC of A$2,640 to A$3,000 per ounce.
Q2. What was Westgold Resources gold production in FY26?
Ans. A record 387koz.
Q3. Does the Company carry debt?
Ans. No. It reports a debt-free and unhedged balance sheet.
Q4. What is the Company’s FY27 production guidance?
Ans. 385koz to 425koz at an AISC of A$2,980 to A$3,380 per ounce.
Disclaimer
This article is intended for informational purposes only. If you pay attention to the gold mining sector as an investor, then all the data in the content is from third-party sources. Please check out the complete share price and market data info. Investing carries a high risk, and you should only invest at your own risk. Mining Herald has no involvement in the above-listed companies.
Filed under
About the author
Jonathon Brown
Jonathon Brown began his career as a broadcaster, working across markets in British Columbia before moving into financial journalism. Since 2017, he has specialised in stock market reporting, covering emerging companies across the healthcare, technology, mining and consumer sectors. He brings more than 15 years' experience to his reporting. A graduate of Vancouver Island University and the British Columbia Institute of Technology, Jonathon is focused on delivering clear, balanced reporting for investors.